

Junior IRRBB Modelling Specialist
ING Hubs Poland is hiring!
The expected salary for this position: 6100 - 12 500 PLN gross.
The financial ranges specified in the announcement are adjusted and may differ from the range specified in the remuneration regulations.
Are you excited about financial markets and interest rates? Would you like to learn how quantitative models help banks understand and manage financial risk? How about building Python models and analytical tools used across an international banking group?
If that sounds like you, we'd like to meet you. We are looking for a new team member to join our Bank-wide Market and Operational Risk Models team.
We are looking for you, if you have:
- an academic degree or being in the final year of a Master's programme in econometrics, quantitative finance, mathematics, physics, statistics, computer science, or a related quantitative field
- an interest in quantitative modelling in the banking industry
- strong statistical, quantitative, and problem-solving skills
- experience with or knowledge of Python or another programming language
You’ll get extra points for:
- knowledge of or interest in IRRBB modelling topics such as behavioural modelling, replication portfolios, earnings-at-risk and valuation frameworks
- experience with databases, data modelling, data preparation, and data quality control
Your responsibilities:
You will work alongside experienced quantitative modellers and learn how models move from an analytical idea through development, testing, review, and ultimately into use across the bank.
You will:
- contribute to model design, coding, and testing
- participate in model submissions and internal reviews
- build analytical tools to better understand and manage financial risks
Information about the team:
The Mar&Ops Model department is an international team of highly qualified professionals specializing in the development and management of market and operational risk models.
Our ALM models are an important part of ING's risk management framework and include behavioural models (e.g. prepayment), replication and hedging models, and stress-testing models and techniques. They are used by local Risk Management units across ING, as well as by the Group Risk function.
Our team works closely with colleagues in Amsterdam to develop financial risk models used across the ING Group.
The role naming convention in the global ING job architecture will be “Model Developer I”.
 Your place of work
Explore the area
Questions? Just ask
ING Recruitment team
ING’s vision is to unlock our people’s full potential through our inclusive culture where everyone has the opportunity to develop and have impact for our customers and society. To achieve this vision, our policies support diversity, equity, and inclusion. As an equal opportunity employer, we do not tolerate discrimination of any kind with regard to age, gender, gender identity, cultural background, experience, religion, race, ethnicity, disability, family responsibilities, sexual orientation, social origin, or any other status protected by applicable law. If you require any assistance or if we can accommodate you in any way when participating in our application and/or interview process, please email the recruiting contact listed for the relevant position. We will be happy to work with you to ensure a fair and accessible process. Read more about our commitment to diversity, inclusion and belonging here.
More for you
-
 Retail Banking By providing the right information and tools at the right time, supported by clear and easy products, ING strives to empower people to make better financial decisions. May 15, 2024 Article Expertise & Teams Retail Banking Related Content
-
Technology What makes ING Tech such a great place to work? Ask our colleagues! They’ll tell you about how we’re applying technology on a global scale to provide a superior customer experience that’s easy, instant, personal, and relevant. May 15, 2024 Article Expertise & Teams
-
Risk Management Identify, assess, and mitigate risks to protect our assets. Be the strategist safeguarding our enterprise. May 15, 2024 Article Overview Expertise & Teams
-
About ING ING is a global bank with a strong European base. More than 60,000 colleagues serve around 38 million customers and corporate clients in over 40 countries. June 28, 2024 Article Culture
-
Business and Wholesale Banking specialism Join ING's Business & Wholesale Banking team to provide top financial services to corporate clients. Explore diverse roles and make an impact globally. August 12, 2024 Article Expertise & Teams Wholesale Banking Related Content
-
Audit Services at ING Drive integrity and transparency in our financial operations by ensuring compliance and identifying areas for improvement. Be the watchdog that safeguards our organisational health. August 12, 2024 Article Expertise & Teams
-
Business support & Business Management Empower our teams with seamless operational support and strategic management. Be the backbone that keeps our business running smoothly and efficiently. August 12, 2024 Article Expertise & Teams
-
Client and Business Services Enhance client satisfaction and streamline business processes. Be the trusted partner delivering excellence in every interaction. August 12, 2024 Article Expertise & Teams Related Content
-
Communications and Brand Experience Here, you'll craft compelling narratives and create engaging brand experiences. Make it your job to influence how the world sees our brand with your creative and fast-paced work. August 12, 2024 Article Expertise & Teams
-
Compliance Join ING's Compliance team to combat fraud and corruption. Ensure adherence to regulations, safeguard our reputation, and act as our moral compass. August 12, 2024 Article Expertise & Teams Related Content
-
Corporate and Facility Services Manage our physical and corporate environments to optimise efficiency. Be the curator of spaces where innovation thrives. August 12, 2024 Article Expertise & Teams Related Content
-
Customer Experience Elevate every touchpoint to create exceptional customer journeys. Be the architect of client satisfaction and loyalty. August 12, 2024 Article Expertise & Teams Related Content
-
Data Modelling and Analytics Harness data to draw out insights and inform decision-making. Be the analytical powerhouse fuelling our strategic moves. August 12, 2024 Article Expertise & Teams Related Content
-
Finance Manage our financial health and guide our economic strategies. Be the financial steward that ensures our prosperity. August 12, 2024 Article Expertise & Teams Related Content
-
Human Resources Cultivate our talent and foster an engaging work culture. Be the champion of our people and their potential. August 12, 2024 Article Expertise & Teams Related Content
-
Group Treasury Oversee our liquidity and capital management to ensure financial stability. Be the strategist managing our financial resources with precision. August 12, 2024 Article Expertise & Teams Related Content
-
Innovation Discover innovation jobs at ING, driving forward-thinking solutions and creativity. Explore roles in Tech, Risk Management, and Operations. Shape the future with us. August 12, 2024 Article Expertise & Teams Related Content
-
Know Your Customer Join ING's Know Your Customer team to investigate and analyze client information, ensuring regulatory compliance and effective risk management. August 12, 2024 Article Expertise & Teams Related Content
-
Legal and Corporate Governance Provide expert legal advice and ensure compliance at ING. Join us to uphold governance standards and support our international growth with innovative solutions. August 12, 2024 Article Expertise & Teams Related Content
-
Leadership Inspire and lead teams at ING, guiding them to achieve our vision. Drive change and propel the organization to new heights in growth and innovation. August 12, 2024 Article Expertise & Teams Related Content
-
Procurement Optimize purchasing processes and secure top resources for ING. Be the expert negotiator ensuring value and quality in procurement for our business. August 12, 2024 Article Expertise & Teams Related Content
-
Relationship Management Build and nurture client relationships at ING. Provide expert advice and tailored solutions for business and individual needs, fostering trust and collaboration. August 12, 2024 Article Expertise & Teams Related Content
-
Transformation Join ING's Transformation team to drive change and shape the future of banking. Explore impactful career opportunities today!
August 12, 2024 Article Expertise & Teams Related Content -
International Talent Programme ING's International Talent Programme offers global traineeships with three rotations, including one abroad, focusing on personal, professional, and organizational development. August 13, 2024 Overview Early Careers: Global Graduate Programme Programmes
-
Wholesale Banking Our purpose is to empower people to stay a step ahead in life and in business. So whatever financial needs of our corporate clients have, whether they are looking to expand and want strategic advice, or just want more efficient day-to-day banking, we support their business ambitions. August 13, 2024 Overview Expertise & Teams Wholesale Banking Related Content
-
Locations Explore our locations around the globe and discover where you want to work. August 13, 2024 Overview Expertise & Teams Related Content
-
Expertise & Teams At ING, our diverse teams excel across all banking sectors. From Retail Banking to Wholesale Banking, Risk Management, and Tech, we provide tailored solutions and innovative strategies. August 13, 2024 Overview Expertise & Teams Related Content
-
Working at ING Working at ING means working with great people: friendly, collaborative and (we think) fun! We empower the people around us and our customers to stay a step ahead. A job at ING comes with autonomy and the expectation to drive progress, deliver a superior customer experience and create a more sustainable future for people and planet. August 13, 2024 Article Culture
-
Early Careers At ING, we're not just about banking. We also want to empower you to explore a world brimming with opportunities. Our early careers offerings—ranging from trainee and talent programmes to specialised IT classes—are designed to ignite your passion and accelerate your journey of professional and personal growth. August 13, 2024 Overview Students & Graduates Related Content
-
Working at ING in the Netherlands There’s a good chance we’ve met before. If you’ve watched the Dutch football team play, flown out of Schiphol airport or visited the Rijksmuseum, it’s likely you’ll have seen our orange lion. The Netherlands is our home, and we’re proud of our strong Dutch heritage. August 13, 2024 Article Overview Location Spotlight Related Content
-
Working at ING in Australia Over 20 years ago, we launched the country’s first high-interest, fee-free online savings account. Today, we continue to lead with innovative products like home loans, superannuation, credit cards, and more. August 13, 2024 Article Overview Location Spotlight Related Content
-
Working at ING in Belgium With over 6,000 employees in Belgium, we’re a significant employer. Research shows that our vibrant ‘orange’ culture sets us apart. We offer impactful roles in an inclusive and collaborative work environment, competitive benefits, great flexibility thanks to our hybrid work model and opportunities to grow your career. August 13, 2024 Article Overview Location Spotlight Employee Stories Related Content
-
Working at ING in Germany We’ve got over 9 million customers in Germany who trust us, making us the third largest bank in the country. Our core business includes savings accounts, mortgages, investment products, consumer loans and current accounts for private customers. August 13, 2024 Article Overview Culture Expertise & Teams Students & Graduates Benefits ING Hubs Early Careers: Global Graduate Programme Early Careers: Local Opportunities Location Spotlight Employee Stories
-
Working at ING in Italy As a trusted partner for millions of corporate and retail clients, ING is active in Italy with its two business lines: Wholesale & Retail Banking. Our almost 1,300 employees are spread across our office in Milan and our branches and stores in 16 cities. August 13, 2024 Article Overview Location Spotlight Related Content
-
Working at ING in Luxembourg At ING Luxembourg, we are committed to innovation, sustainability, and excellence. As part of the global ING Group, we provide comprehensive financial services, including banking, investments, insurance, and pensions. August 13, 2024 Article Overview Location Spotlight Related Content
-
Working at ING in the Philippines ING Hubs Philippines started in 2013 under the name of ING Global Shared Operations, offering in-house processing services for financial markets, lending, and trade and finance services (TFS) to some of ING’s Wholesale Banking branches in Asia. August 13, 2024 Article ING Hubs Location Spotlight Related Content
-
Working at ING in Poland At ING in Poland, we offer exciting opportunities across two main entities: ING Hubs Poland and ING Bank Śląski. Together, they form a critical part of ING’s global operations, driving innovation, customer service excellence, and sustainable finance. August 13, 2024 Article Overview ING Hubs Location Spotlight Related Content
-
Working at ING in Romania At ING in Romania, we offer exciting opportunities across two main entities: ING Hubs Romania and ING Bank Romania. Together, they form a critical part of ING’s global operations, driving innovation, customer service excellence, and sustainable finance. August 13, 2024 Article ING Hubs Location Spotlight Related Content
-
Trabajar en ING España Somos un equipo de más de 1.600 personas animadas por un mismo propósito: aportar nuestro granito de arena para ayudar a nuestros clientes a crearse un futuro mejor, proporcionándoles las herramientas que necesitan para llegar adonde quieren. August 13, 2024 Article Overview Expertise & Teams Benefits Early Careers: Global Graduate Programme Location Spotlight
-
Global Analytics Graduate Programme (ITP) Join ING's Global Analytics Graduate Programme to harness data for smarter banking. Experience three rotations, global impact, and drive innovation. August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Programmes
-
Business Banking International Talent Programme Business Banking is one of the three pillars of Retail Banking. In Business Banking we serve three types of customers: self-employed, SMEs and mid-corporates. August 13, 2024 Overview Students & Graduates Early Careers: Global Graduate Programme Early Careers: Local Opportunities Related Content
-
Philipines Hubs Discover ING Hubs Philippines – a global hub for IT, finance, risk management, and data analytics, supporting 40 countries with over 4,800 employees. August 13, 2024 Overview ING Hubs Related Content
-
Working in ING Hubs Poland Established in 2003 and located in Katowice and Warsaw, ING Hubs Poland provides IT and operational services to all ING units. August 13, 2024 Overview About ING Business ING Hubs Related Content
-
Romania Hubs ING Hubs Romania offers 130 services in software development, data management, non-financial risk & compliance, audit, and retail operations to 24 ING units worldwide, with the help of over 1,700 high-performing engineers and risk and operations professionals. August 13, 2024 Overview ING Hubs Related Content
-
Slovakia Hubs ING Hubs Slovakia dates back to 2009 and was built on the longstanding expertise and established presence of ING in Slovakia. Our current team of 1,400 employees provides expert services and drives change and improvement in ING processes. August 13, 2024 Article ING Hubs Related Content
-
Türkiye Hubs Established in 2023, ING Hubs Türkiye offers tech and data analytics services inside ING Group with its team of data experts, developers and other professionals working in the Istanbul office. August 13, 2024 Article ING Hubs Related Content
-
Wholesale Banking in EMEA The EMEA region is the largest of the three Wholesale Banking regions with 23 countries, serving as a gateway to Europe for American and Asian multinationals. Our network is the driving force behind our business strategy. We are working together across borders to make a difference in the markets and sectors we operate in. August 13, 2024 Article Expertise & Teams Wholesale Banking Related Content
-
Wholesale Banking in APAC Nasz zasięg Wholesale Banking w regionie APAC obejmuje Hongkong, Pekin, Szanghaj, Tajwan, Koreę Południową, Japonię, Indonezję, Indie, Filipiny i Wietnam. August 13, 2024 Article Expertise & Teams Wholesale Banking Location Spotlight Related Content
-
Human Resources International Talent Programme Join ING's HR International Talent Programme. Experience three rotations, shape our culture, and drive innovation in HR across the globe. Apply now! August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Related Content
-
Operations and Change International Talent Programme Join ING's Operations and Change International Talent Programme. Drive strategic initiatives and lead transformative projects in banking! August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Related Content
-
Retail Banking International Talent Programme As a retail banking trainee, your work will directly impact millions of customers. And if you’ve got smart ideas for how to push banking forward, you’ll be encouraged to make them happen - right from day one. August 13, 2024 Article Students & Graduates Retail Banking Early Careers: Global Graduate Programme Related Content
-
Risk International Talent Programme As a Risk trainee, you’ll be working on strategies to manage and prevent risks to our business. The financial consequences are big, the margin for error tiny. Are you up to the challenge? August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Related Content
-
Tech International Talent Programme As a Tech trainee, you’ll be working at the cutting edge of financial technology at an incredibly interesting time. Your work will have a direct impact on our customers throughout the world. Join us and shape the future of banking. August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Early Careers: Local Opportunities Related Content
-
Wholesale Banking International Talent Programme As a Wholesale Banking trainee, you’ll play an active role in the dynamic, globe-straddling world of corporate banking. You’ll be doing essential work as a trusted advisor for big clients, on big deals.
August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Related Content -
Security Join ING Security to protect people, assets, and data. Be part of a mission to keep the bank safe and trusted globally with innovative, automated solutions. August 21, 2024 Article Expertise & Teams Employee Stories Related Content
-
Japke Kaastra, Financial Health in the Netherlands It only takes a few motivated people to initiate positive change. September 30, 2024 Article Culture Employee Stories
-
Lehna - ITP Wholesale Banking Curiosity lights the path, mentorship shapes the journey October 01, 2025 Article Employee Stories Related Content
-
Irene Ribot, Customer Journey Expert Customer Journey Expert, Squad Digital and Client Development. ING aims to be the best digital bank. That includes offering accessible, intuitive digital payment methods November 01, 2024 Article Retail Banking Employee Stories Related Content
-
Benefits in Belgium This is what can we offer you. November 05, 2024 Overview Benefits Related Content
-
Customer Journey Expert Providing our customers with the best possible experience, anytime and anywhere. November 01, 2024 Article Expertise & Teams Related Content
-
ING, a Pioneering Employer At ING we are committed to diversity, inclusion and belonging, not just because it is the right thing to do. November 07, 2024 Article Culture Diversity, Inclusion & Belonging Benefits Related Content
-
Olivia and Anouk, Corporate Investments Wholesale Banking "Combining ambition with parenthood: 'it's not always easy, but it's possible'" November 13, 2024 Article Culture Wholesale Banking Employee Stories Related Content
-
Karl Kluun, Loan Capital Markets Wholesale Banking "You're a source of valuable information for your clients" November 14, 2024 Article Wholesale Banking Employee Stories Related Content
-
Darlene and Mathijs, Wholesale Banking Transaction Services "Our ambition? To be the bank our clients call first, and to grow together with them" November 14, 2024 Article Wholesale Banking Employee Stories Related Content
-
Gabriela Matei, Trainee Finance "A journey full of surprises" November 15, 2024 Article Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Souad Goossen, Trainee Finance "Building bonds for life – this is how I had imagined a traineeship to be" November 15, 2024 Article Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Leeuwarden ING Customer support If you’re a customer and you have a question or problem, you can reach us right away in your app. It’s safe and fast. Our colleagues are here to help. November 18, 2024 Overview Retail Banking Location Spotlight Related Content
-
Benefits at ING Bank Śląski At ING, we believe in a world where everyone has rights to develop on your own terms. "Do your thing" applies not only to our clients, but also to over eight thousand working people. November 19, 2024 Overview Benefits ING Bank Related Content
-
Working at ING Americas Be Part of What's Next. November 19, 2024 Overview Culture Benefits Location Spotlight
-
Kinga Glama, Trainee Risk "I wanted to work closer to clients and I found that opportunity here" November 20, 2024 Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Benefits in Germany We want to be more than an employer and to offer more than a job. That’s why we support our employees not only in their work, but also in many other aspects of life. So that everyone can reach their full potential – both professionally and personally. November 20, 2024 Overview Benefits Related Content
-
Hybrid Working November 19, 2024 Overview Benefits Wholesale Banking Related Content
-
Herman Martens, Trainee Risk "You have to push your boundaries, otherwise nothing will happen" November 22, 2024 Article Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Women in Tech story: Zhilla Noorbakhsh Global Head of Technology at ING Zhilla is a strong advocate for creating opportunities and empowerment for women, particularly when it comes to women in the tech sector. More than 25 years ago, she was one of only six women studying software engineering at university in her native Iran. Moreover, in her first job, she was the only female employee in the entire company. November 24, 2024 Article Expertise & Teams Employee Stories Related Content Homepage - Testimonials
-
Tech Chapter Lead Katja Schuitemaker IT Chapter Lead Katja Schuitemaker at DEV World: How an ancient theory can help to predict the future November 25, 2024 Article Expertise & Teams Employee Stories Related Content
-
Acanthus Amsterdam Zuidoost ING headquarters in Amsterdam Zuidoost, the Netherlands. November 25, 2024 Article Location Spotlight Related Content
-
Our ERG's in the Netherlands Our networks bring colleagues together through courageous conversations and other events November 26, 2024 Overview Culture Diversity, Inclusion & Belonging Related Content
-
Want to get a taste of work experience? With an internship at ING! Expect exciting projects and a deep insight into Germany's most popular bank! Try it out for an internship or working studies. November 26, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content
-
ING in the UK Helping you unlock your full potential November 26, 2024 Benefits Related Content
-
Theory meets practice: Dual Study Programme at ING Theory at university, practice at Germany's most popular bank: start your Dual Study Program in business administration, business technology or UX design. November 27, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content
-
Work-study program User Experience Design For our customers, it is of the utmost importance that our online and app products are intuitive and easy to use. That’s why our UX experts are part of the project from day one for every new development. November 27, 2024 Article Students & Graduates Early Careers: Local Opportunities Related Content
-
Banking in The Netherlands Making a difference for our millions of customers, our planet, and society. November 27, 2024 Overview Expertise & Teams Retail Banking Related Content
-
Application process in Germany From the first click to onboarding: how to apply at Germany's most popular bank! November 27, 2024 Overview Hiring Process and FAQs Related Content
-
Benefits ING España Discover the benefits created by and for the people who make ING what it is. November 27, 2024 Article Benefits Related Content
-
ING - Working in Singapore October 10, 2024 Overview Culture Diversity, Inclusion & Belonging Benefits Learning & Development Wholesale Banking Location Spotlight Related Content
-
Work-study program Business Administration What can you expect from working with us? The full experience. You truly work with us and see what’s going on. November 28, 2024 Article Students & Graduates Early Careers: Local Opportunities Related Content
-
Business Computing Find out how to control complex processes, and how to find the right solutions in a digital bank that help customers keep their finances in order easily and stress free. November 28, 2024 Article Students & Graduates Early Careers: Local Opportunities Related Content
-
Business Client Advisor, Zwolle-Deventer Ring Helping entrepreneurs to achieve their ambitions. November 28, 2024 Article Expertise & Teams Employee Stories Related Content
-
Apprenticeship You are the next generation in digital banking: start your apprenticeship now
at ING Germany - e.g. in IT or dialog marketing. November 28, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content -
Wholesale Banking in the Netherlands Superior value to our clients, putting sustainability at the heart November 28, 2024 Overview Expertise & Teams Wholesale Banking Related Content
-
Apprenticeship, internship, studies: Early careers at ING Germany Curious, motivated and ready to rock? Then take off as a young talent at ING Germany. November 28, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content
-
The best thing about our work? Doing something meaningful! Get to know Dan-Radu from Wholesale Banking November 29, 2024 Article About ING Business Wholesale Banking Early Careers: Global Graduate Programme Employee Stories Related Content
-
Head of Security Analytics Eduardo Bárbaro The art of integrating analytics into cyber security. ‘At ING, we dare to put proofs-of-concepts into production – even in such a
complex domain as cyber security’. November 29, 2024 Article Expertise & Teams Employee Stories Related Content -
With a Master's or Bachelor's degree: Junior Expert Programme at ING Germany With a Bachelor‘s or Master‘s degree, the digital world of finance is at your fingertips. Dive deep as a Junior Expert for 12 months and discover the wide range of opportunities within your track. December 02, 2024 Overview Expertise & Teams Students & Graduates Early Careers: Local Opportunities Related Content
-
Building cultural bridges makes teams more innovative Multicultural teams - good for new ideas or more of a challenge? Qian talks about herexperiences in her everyday work life. December 02, 2024 Article Culture Diversity, Inclusion & Belonging Employee Stories Related Content
-
IT apprenticeships IT specialist for system integration or application development
IT specialist for application development
IT Specialist Data and Process Analysis
Merchants Digitization Management
IT gets you excited. You love to think analytically and conceptually. You courageously dive into complex systems. If you’re also interested in the real human user behind all this, then this is the perfect apprenticeship for you. December 03, 2024 Article Students & Graduates Early Careers: Local Opportunities Related Content -
Luca - ITP Risk Growing means finding your ‘uncomfortzone’ December 03, 2024 Article Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Apprenticeship to become a bank clerk We’ll do everything we can to help you understand the needs of your customers. And you’ll help us reach our goal of making customers happy! You won’t just be crunching numbers: you’ll be gaining a feel for how to make banking easier. December 03, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content
-
FAQ's and unfiltered answers. What are the most Frequently Asked Questions to ING as an employer? We asked our trainees to give their (unfiltered) opinions about the programme, their experiences and the interview procedure. Tune in! December 03, 2024 Overview Culture Students & Graduates Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Lisa - ITP HR Discover yourself, choose your change December 03, 2024 Article Employee Stories Related Content
-
Rana - ITP Analytics The power of asking for help leads to a shared success December 03, 2024 Article Employee Stories Related Content
-
Valérie - Fraud specialist In the fraud department, we complement and understand each other well December 03, 2024 Article Employee Stories Related Content
-
Apprenticeship to become a dialogue marketing clerk In this apprenticeship, you expand your professional, social and methodological capacities: You can get started right away and take on our customers’ needs. For you, it will mostly involve telephone and written contact with customers. We’ll be there to support you and show you the way. December 03, 2024 Overview Students & Graduates Early Careers: Local Opportunities Related Content
-
Jan Vercauteren - HR Digitalization Expert Dad, I don’t feel comfortable in my own skin...
I might actually be in the wrong skin. December 03, 2024 Article Culture Diversity, Inclusion & Belonging Employee Stories Related Content -
Early Careers in The Netherlands Want to start your career at ING? Check the latest career opportunities via our local graduate programmes, starter positions or internships. Find a position that matches your skills. December 03, 2024 Overview Students & Graduates Early Careers: Global Graduate Programme Early Careers: Local Opportunities Related Content
-
Julie - Private Banker at ING After 17 years, it's fair to say that I feel good here December 03, 2024 Article Expertise & Teams Wholesale Banking Employee Stories Related Content
-
Cedric - Private Banker at ING I feel privileged to be their trusted advisor December 03, 2024 Article Expertise & Teams Wholesale Banking Employee Stories Related Content
-
Maxime - Private banker at ING It's all about taking time and being curious. December 03, 2024 Article Expertise & Teams Employee Stories Related Content
-
Laia - Head of private banking Brussels at ING Private banking will continue to grow in the coming years. December 03, 2024 Article Expertise & Teams Wholesale Banking Employee Stories Related Content
-
Tech Class The place to be if you want to be a top Tech specialist December 04, 2024 Overview Expertise & Teams Students & Graduates Early Careers: Local Opportunities Programmes
-
Herbert Fikkers, Director Sustainable Investments High-risk investments in a sustainable future. Herbert Fikkers December 06, 2024 Article Retail Banking Employee Stories Related Content
-
Roll up your sleeves! The courage to change and be flexible Sonja from HR never really planned to work at a bank. But the vibe at the interview won her over. December 09, 2024 Article Culture Students & Graduates Early Careers: Global Graduate Programme Employee Stories Related Content
-
It is important to keep an open mind Beau tells us about the challenges she faces in an international working environment and how they helped her grow. December 09, 2024 Article Diversity, Inclusion & Belonging Wholesale Banking Employee Stories Related Content
-
The housing team in the Netherlands 'Everything to make the customer's housing wish come true' December 10, 2024 Article Retail Banking Employee Stories Related Content
-
Culture in the Netherlands At ING, you'll work with great people: friendly, collaborative, and (we think) fun! Known for an excellent work culture, great benefits, and engaging work, we believe in sustainable progress for everyone, not just a few. December 10, 2024 Overview Culture Diversity, Inclusion & Belonging Employee Stories Related Content
-
Nyka - Change Expert Moving freely. December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Amina - Financial Crime Specialist Risk is life December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Anna - Chapter Lead Data Analysis Carte blanche to do your job. Even in Risk December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Adyasha - Cloud Native Engineer Making people's lives easier December 06, 2024 Article Employee Stories Related Content
-
Benoît - Credit Restructuring Officer They gave me the time I needed to learn my job December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Matthieu - Chapter Lead & Front End Tech Lead We have the same challenges as companies in Silicon Valley December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Sara - Development Engineer Inspiring women and kids to choose Tech. December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Rocio Lopez Ligula elit leo montes congue et wisi id lacus tellus enim. Vitae dignissim sit est mauris orci eros ac et habitasse pretium. October 02, 2024 Article Employee Stories Homepage - Testimonials
-
Financieel Coach De persoonlijke touch binnen de digitale bank December 13, 2024 Overview Retail Banking Early Careers: Local Opportunities Related Content
-
Charis Pattikawa Lead HRBP for Wholesale Banking The support I get from ING is unrivalled, Charis Pattikawa Lead HRBP for Wholesale Banking December 17, 2024 Article Expertise & Teams Employee Stories Related Content
-
Roopam - Site Reliability Engineer Building relationships is just as important as writing code. December 18, 2024 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Jolien - Information Security Governance Expert If we see something that needs to be improved, we tackle it. December 18, 2024 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Maral - Risk Modeller Engineering and risk modelling are more closely related than you might think. December 18, 2024 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Marissa Gijsen, Safe Business Officer in Business Lending ING Marissa Gijsen, Safe Business Officer in Business Lending at ING in the Netherlands December 30, 2024 Article Retail Banking Employee Stories Related Content
-
Todor Mohan Credit Risk Modeller at ING Todor Mohan Credit Risk Modeller at ING: It’s super easy to connect with the other members of my team. Most of us come from abroad so we share the same experiences January 03, 2025 Article Expertise & Teams Employee Stories Related Content
-
Customer Journey Expert and Chief Product Owner Shashank Jhawar Customer Journey Expert and Chief Product Owner: I wouldn’t want to miss the big shift we’re heading for in trade finance. November 05, 2024 Article Expertise & Teams Employee Stories Related Content
-
Pallav Jha, Customer Journey Expert "The process to get from a concept to something that works for our customers is infinitely fascinating" November 15, 2024 Article Employee Stories Related Content
-
We are a bank for banks Colleagues from all over the world work together in the Asset Securitisation team – but what exactly do they do? January 20, 2025 Article Culture Expertise & Teams Wholesale Banking Employee Stories
-
It needs to come from the heart How Thomas balances work and volunteering. January 20, 2025 Article Culture Employee Stories Related Content
-
Mats, Trainee Business Banking "Amsterdam or Milan: never a dull moment" November 15, 2024 Article Retail Banking Early Careers: Global Graduate Programme Early Careers: Local Opportunities Employee Stories Related Content
-
Tech Conference ING booth Meet us at Tech Conferences in Europe January 22, 2025 Article Expertise & Teams Events Events
-
Amit, Java Developer & cloud native expert December 06, 2024 Article Expertise & Teams Employee Stories Related Content
-
Get to know us The best way to learn about who we are and how we work together is directly from our colleagues. January 22, 2025 Article Overview Culture Expertise & Teams Benefits Employee Stories Related Content
-
FAQ Internships Check out all the ins and outs of our internships. January 16, 2025 Overview Culture Students & Graduates Early Careers: Local Opportunities
-
Fadi Esak, Financial Coach Taking that extra step for the customer February 14, 2025 Article Retail Banking Early Careers: Local Opportunities Employee Stories Related Content
-
Wholesale Banking w Ameryce Północnej Jesteśmy obecni w Meksyku, Dallas, Houston, Los Angeles i Nowym Jorku, gdzie łączymy głęboką wiedzę sektorową z szeroką gamą produktów finansowych. August 13, 2024 Article Expertise & Teams Wholesale Banking Related Content
-
Deri from ING Hubs Poland Tips for fostering inclusion at the workplace during Ramadan February 19, 2025 Article Employee Stories Related Content Homepage - Testimonials
-
Become a Customer Journey Expert | ING Belgium Discover Customer Journey Expert careers at ING Belgium. Improve customer experiences, drive innovation and work with diverse teams. February 21, 2025 Overview Expertise & Teams
-
Deep Fakes: How to battle deep fakes and AI-powered scammers On 18 July 2024, ING’s Security & Fraud Chapter Leads Aurel-George Proroocu and Mihai Roman will be speaking at the WeAreDevelopers World Congress in Berlin. It’s the world’s leading event for developers and tech decision-makers. February 25, 2025 Article Expertise & Teams Employee Stories Related Content Homepage - Testimonials
-
ING, a pioneering employer At ING we are committed to diversity, inclusion and belonging, not just because it is the right thing to do! November 29, 2024 Article Diversity, Inclusion & Belonging Related Content
-
Us women are stronger than we think! From intern to manager: find out all about Sanja's career path at ING. January 22, 2025 Article Culture Wholesale Banking Early Careers: Local Opportunities Related Content
-
From Frankfurt to Amsterdam and back From Trainee to Chapter Lead – Merit shares her exciting career journey at ING Germany. January 23, 2025 Article Culture Students & Graduates Early Careers: Local Opportunities Employee Stories Related Content
-
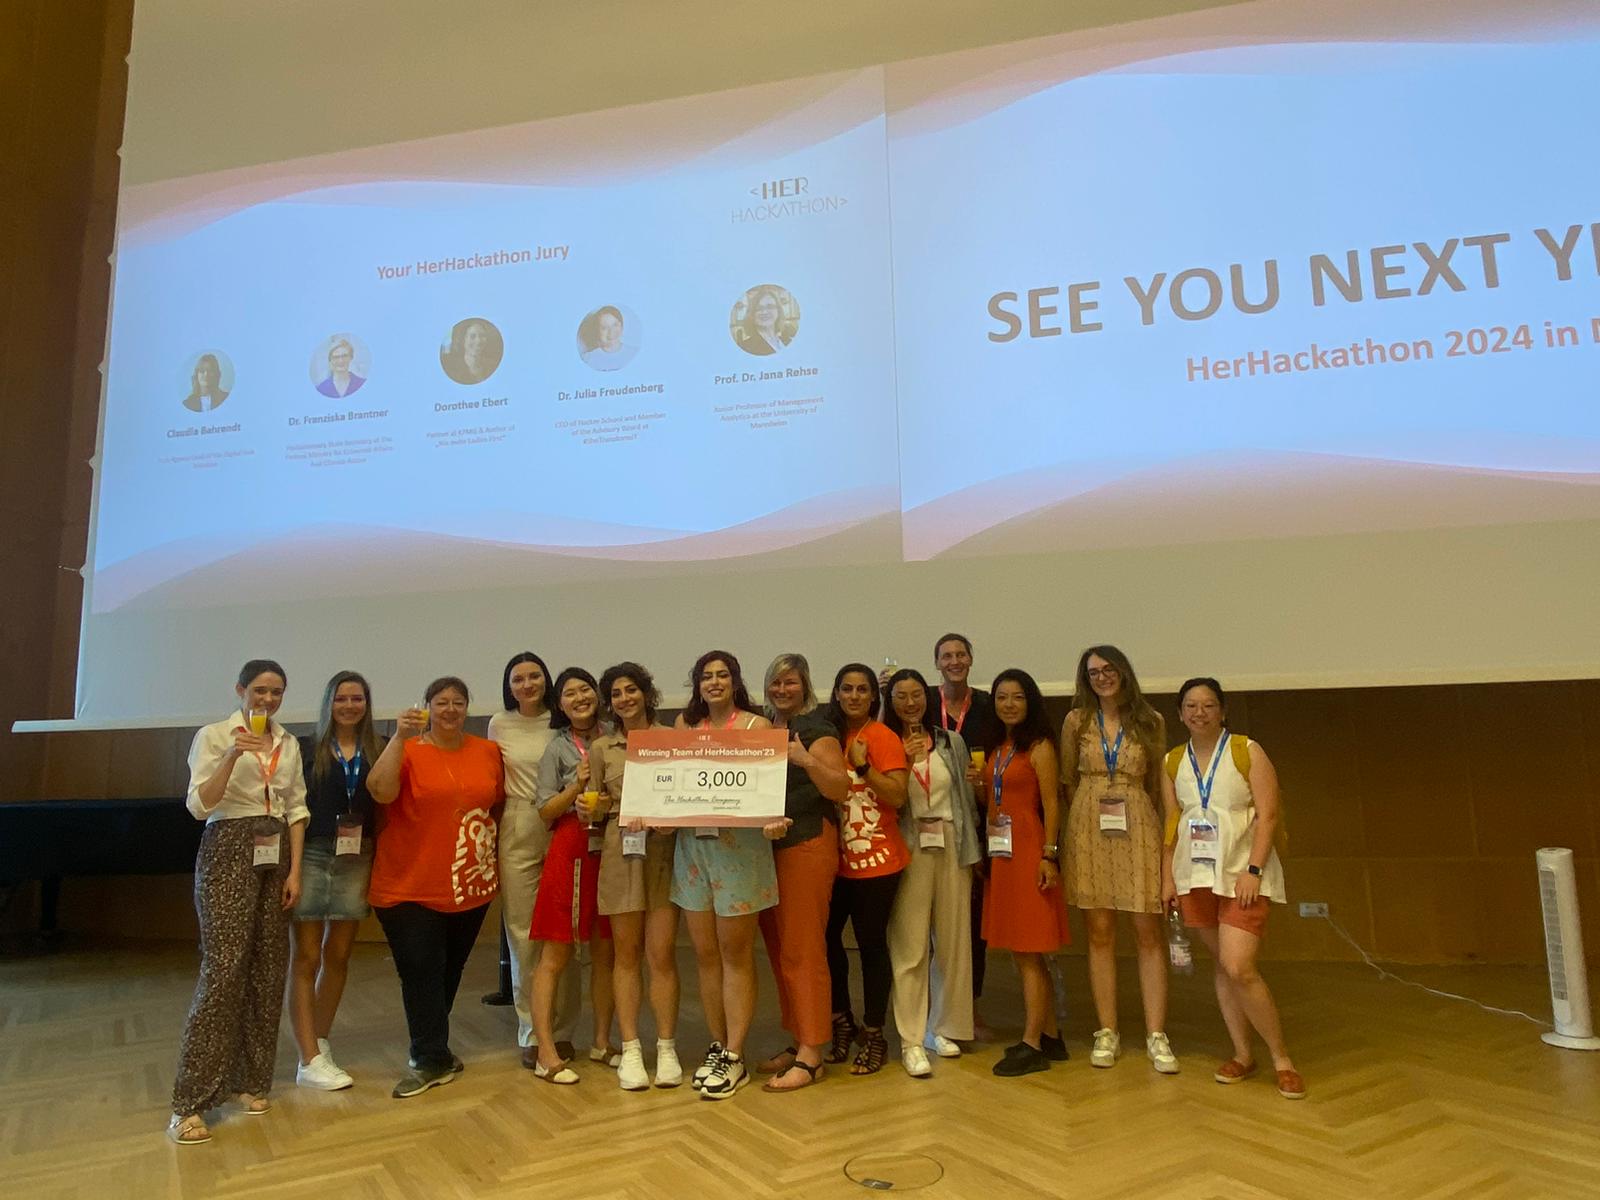
HerHackathon – a chance to empower women in tech Female power, team spirit, innovation – HerHackathon 2023 January 27, 2025 Article Expertise & Teams Employee Stories Related Content
-
Thoughts on Ramadan As a devout Muslim, how does Ahad combine the holy month of Ramadan with his full-time job? He shares his experiences with us and explains why Ramadan is about more than just abstaining from food and drink. January 31, 2025 Article Culture Diversity, Inclusion & Belonging Employee Stories Related Content
-
Benefits in the Netherlands At ING, our mission is to ‘empower people to stay a step ahead in life and in business’ – not only our customers, but also our employees. In line with this, we offer a unique – and sometimes even surprising – benefits package. October 01, 2024 Overview Benefits Related Content
-
International Women’s Day 2025 Progress check on our gender equity goals. March 05, 2025 Article Diversity, Inclusion & Belonging Related Content
-
Beste - Customer Journey Expert and Product Owner I look for constant personal and professional growth March 17, 2025 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Stefan - Customer Journey Expert and Product Owner It’s not just about what’s important to ING, but to the customer March 17, 2025 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Vincent - Data Analyst Data helps you make smarter decisions March 17, 2025 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Lise - Customer Journey Expert and Product Owner Knowing that your customers are grateful for what you do March 17, 2025 Article Expertise & Teams Employee Stories Homepage - Testimonials
-
Bring color into your job: Employee networks at ING Germany You prefer diversity? So do we: Our employee networks unite people with the most diverse life paths and experiences - discover them now and join us! December 03, 2024 Overview Culture Diversity, Inclusion & Belonging
-
Financial Markets Graduate Programme Providing risk distribution and hedging for institutional and corporate clients March 20, 2025 Overview Expertise & Teams Students & Graduates Wholesale Banking Early Careers: Local Opportunities Programmes
-
Capital Markets & Advisory - Early Career Group Explore your talent to become an investment banker March 24, 2025 Overview Expertise & Teams Students & Graduates Wholesale Banking Early Careers: Local Opportunities
-
Getting out of your comfort zone – and into a positive mindset Marlly came to ING Germany in 2022 and took part in the Junior Expert Program. After just three months, she already found her professional home and started full steam ahead as a Feature Engineer. April 24, 2025 Article Culture Diversity, Inclusion & Belonging Early Careers: Local Opportunities Employee Stories Related Content
-
Niki & Sebastiaan | Capital Markets & Advisory ‘A unique opportunity to dive deeper into the world of investment banking’ May 23, 2025 Article Culture Expertise & Teams Students & Graduates Wholesale Banking Early Careers: Local Opportunities Employee Stories Homepage - Testimonials
-
Meet us at European Women in Tech 2025 Keynote speaker on mainstage at European Women in Tech in Amsterdam, Bidisha Agarwal, ING Tech Lead in Amsterdam June 13, 2025 Article Expertise & Teams Events
-
How Filip looks into the crystal ball for our business Filip on ING’s Unique Culture, International Cooperation, and How It Stands Apart from Conventional Banks September 03, 2025 Article Culture Early Careers: Local Opportunities Employee Stories Related Content
-
Provide perfect financial advice The trusted voices behind life’s most important financial decisions. September 04, 2025 Expertise & Teams Retail Banking Wholesale Banking ING Bank
-
Working at ING in Dublin At ING Dublin, we are committed to innovation, sustainability and excellence. As part of the global ING Group, our office plays a key role as a centre of excellence and strategic lending hub, supporting clients across Europe and the Americas with high-quality financial solutions. September 18, 2025 Overview Location Spotlight Related Content
-
LendForward Dublin Graduate Programme Our ING Dublin graduate programme is designed to give you the tools, experience, and support to thrive in a fast-paced, international environment. September 18, 2025 Article Students & Graduates Early Careers: Local Opportunities Programmes
-
Tech in the Netherlands ING Tech: tech that matters in peoples lives December 02, 2024 Overview Expertise & Teams Related Content
-
Alexandre - ITP Finance The best is yet to come October 01, 2025 Article Employee Stories Related Content
-
Julie - ITP Retail banking It's not all strategy and spreadsheets October 01, 2025 Article Employee Stories Related Content
-
Lune - ITP Business Banking The first leap into reality October 01, 2025 Article Employee Stories Related Content
-
Finance International Talent Programme Join ING's Finance International Talent Programme. Experience three rotations, shape key decisions, and fast-track your career in finance globally. August 13, 2024 Article Students & Graduates Early Careers: Global Graduate Programme Related Content
-
Daniel - ITP Tech Doubt to drive - engineering to finance October 01, 2025 Article Employee Stories Related Content
-
Would you like to work at ING on a temporary basis? Are you interested to join ING on a temporary assignment, either as independent contractor or via an agency? You can sign up for one of the talent pools. November 13, 2025 Article Expertise & Teams Related Content
-
Claire | Private banker January 14, 2026 Article Employee Stories Homepage - Testimonials
-
Discover the story of Sophie and Ward Sophie and Ward have both had inspiring journeys at ING. Their paths led them from the public relations team to the Transformation Office and from Amsterdam to New York. Discover their story. February 12, 2026 5 Article Employee Stories
-
ING Story | Lisa - Real Estate Business Banking ‘Real estate holds huge appeal for me. It’s tangible’ February 19, 2026 Article Expertise & Teams Retail Banking Employee Stories Homepage - Testimonials
-
ING Story | Róbin - Business Banking ‘Wow, this client is doing something really cool – and we’re part of it!’ February 19, 2026 Article Expertise & Teams Retail Banking Employee Stories Homepage - Testimonials
-
Life at ING March 06, 2026 Article Culture
-
Isabelle, fraud operations target operating model lead I received the boost I needed and rediscovered the power to take control of my own vitality. September 03, 2025 Article Benefits Employee Stories Homepage - Testimonials
-
Ludovic | Private banker Being a private banker is about being there for your clients whenever they need you. January 12, 2026 Article Employee Stories Homepage - Testimonials
-
The story of Malik Discover how Malik built a feature protecting millions of customers. April 02, 2026 3 minute read Article Employee Stories Related Content
-
Alix | product owner Two years into her role at ING, Alix is the driving force behind SaveUp and InvestUp: two features built around one simple human insight. Discover her story. April 02, 2026 Article Employee Stories Related Content
-
Inès | Product Lead Business Banking Inès had one question: how do we remove friction for entrepreneurs? The answer became a platform built across time zones, disciplines and priorities. Discover her story. April 02, 2026 Article Employee Stories Related Content
-
Instant payments: the people behind the screen Discover how Adeline, Begoña, Corentin and Thierry are revolutionising payments. April 02, 2026 Article Employee Stories Related Content
-
‘What feeds me in my job, above all, is human interaction.’ Melissa supports her customers at every major stage of their lives. What drives her? Human contact and proximity to customers. Read her interview. April 16, 2026 Article Expertise & Teams Retail Banking Employee Stories Related Content
-
Discover the story of Gille. For Gille Varewyck, becoming a personal banker felt like the logical next step. After previous roles in investments and remote advice, he consciously chose a job with more customer contact, more responsibility and more scope to really make a difference. April 20, 2026 Article Expertise & Teams Employee Stories Related Content
-
Discover the story of Caroline For Caroline, it was clear from early on: she wanted to become a personal banker one day. In 2011, she started working at ING immediately after completing her studies. Step by step, she grew into her current role in Brasschaat. What appeals most to her today? Being trusted to guide people through important financial choices. April 21, 2026 Article Expertise & Teams Employee Stories Related Content
-
Celebrating Pride at ING We don’t judge people for their food preference, so why do it for who they love? June 12, 2025 Article Diversity, Inclusion & Belonging Related Content
-
Mathilde | social media expert Mathilde took the opportunity to do a short-term assignment in Amsterdam for 6 months. She tells us about her experience. May 29, 2026 Article Benefits Early Careers: Global Graduate Programme Employee Stories Homepage - Testimonials
-
Maxime | quality control lead – financial crime prevention Maxime worked for 6 months in the Philippines. Discover his story. June 02, 2026 Article Employee Stories ING Bank Homepage - Testimonials
-
Matthieu | chapter lead engineer Matthieu is doing a long term assignement in Sidney. Discover his story. June 02, 2026 Article Employee Stories ING Bank Related Content
-
Anders Maars, ING Business Banking in the Netherlands June 24, 2026 Article Employee Stories ING Bank
-
Working at ING Private Banking As a private banker at ING, you get to know the ambitions, challenges and life goals of your clients, building long-term relationships that go far beyond finance. It’s a great opportunity to accelerate your development while creating lasting value for your clients. July 02, 2026 Article Expertise & Teams ING Bank Related Content
-
Abhishek Mishra is Architect Lead working on ING’s Business Lending Engine What matters most to Abhi though, is the human side of the job. It’s fantastic to work with kind, collaborative Tech colleagues who challenge each other constructively. July 20, 2026 Article Employee Stories
-
Tessa Hamstra, ING Client Services Leeuwarden The role of Tessa Hamstra and her colleagues at Client Services in Leeuwarden is “kind of like a lawyer” for ING customers. July 31, 2026 Article Employee Stories
-
A Tech Lead with logic and heart, Hazel Weakly working at ING “I’ve done a bit of everything, giving me a slightly weird, eclectic mix of expertise,” is how Hazel Weakly describes her career so far. But somehow that all fits perfectly with her current role as Architect and Lead for Guardrails within Engineering & Reliability at ING in Nederland. August 04, 2026 Article Employee Stories
-
Alejandro Gomez Lead Trading Risk Model Validation "Improving ING’s risk models making a better bank" November 06, 2024 Article Employee Stories
-
Maple is ING's head office in Amsterdam Zuidoost. Maple is ING's head office in Amsterdam Zuidoost. Visiting address Bijlmerdreef 109. November 25, 2024 Location Spotlight Related Content
-
Line de Langen, Mental health "Learn to say ‘no’ or ‘I’ll do it tomorrow’. That’s more powerful than saying yes to everything." August 27, 2026 Article Culture Benefits Employee Stories
-
Violeta - ITP Wholesale Banking Learning by doing, and enjoying the challenges. July 20, 2026 Overview Employee Stories ING Bank Related Content



Jobs for you
No jobs viewed
No jobs saved